AUDIT: Quanta / Nexans: The Copper Deficit: Inside the €7.9 Billion Grid Mirage
An analytical review of Nexans' strategic positioning in global grid modernization. We examine their €7.9 billion backlog, Q1 2026 organic growth in Electrification, and the institutional solvency mechanisms driving infrastructure capital expenditure.
Listen on
Listen (episode)SpotifyApple PodcastsRSS
The Cassandra Files — forensic audio drama. Katie audits the books, Marcus kills the spin, Killian opens the file. About · Latest · Themes
Paris, France — October 7, 2026. 14:30. The ambient temperature sits at 62 degrees Fahrenheit beneath an overcast sky, matched only by the persistent, sub-audible hum of high-voltage cables routing power beneath the pavement. Within the corporate narrative of global grid modernization, the atmosphere is pitched as a seamless transition toward renewable electrification. The industry presents a vision of synchronized infrastructure, where offshore wind farms and upgraded terrestrial grids operate in perfect harmony. Yet, a forensic examination of the physical supply chain reveals a reality that resembles a high-stakes poker game, where the deck is entirely stacked with copper futures.
At the center of this industrial pivot stands Nexans, a French cable manufacturing giant asserting its dominance as a definitive architect of global electrification. Under the direction of Chief Executive Officer Julien Hueber, the entity claims a unique positioning as a "pure player" in the sector. The immediate financial pulse appears robust, with Nexans reporting a cautiously optimistic first quarter for 2026, headlined by a 4.9 percent organic growth in its Electrification division. Institutional confidence is further anchored by an adjusted backlog of €7.9 billion, a figure ostensibly providing revenue visibility through 2028.
However, beneath the gloss of these quarterly metrics lies a profound structural conflict. The foundational hardware required to execute this forward-looking capital expenditure is caught in a systemic bottleneck. Driven by a projected 1.5 million-ton global copper deficit by 2027 and transformer lead times extending up to 24 months, the physical constraints of material science are actively colliding with institutional ledger mechanisms. Nexans’ €7.9 billion backlog is rapidly transforming from a guaranteed asset into a massive operational liability.
The Abstraction of Material Costs
To understand the vulnerability of the current grid modernization narrative, one must examine the baseline metrics used to secure institutional funding. In its financial reporting, Nexans standardizes the price of copper at €5,000 per ton. This mechanism is a necessary financial modeling tool; it provides a fixed point that allows the entity to forward-model massive capital expenditures for high-voltage networks. Without a standardized material cost, securing institutional capital for multi-year infrastructure projects becomes mathematically impossible.
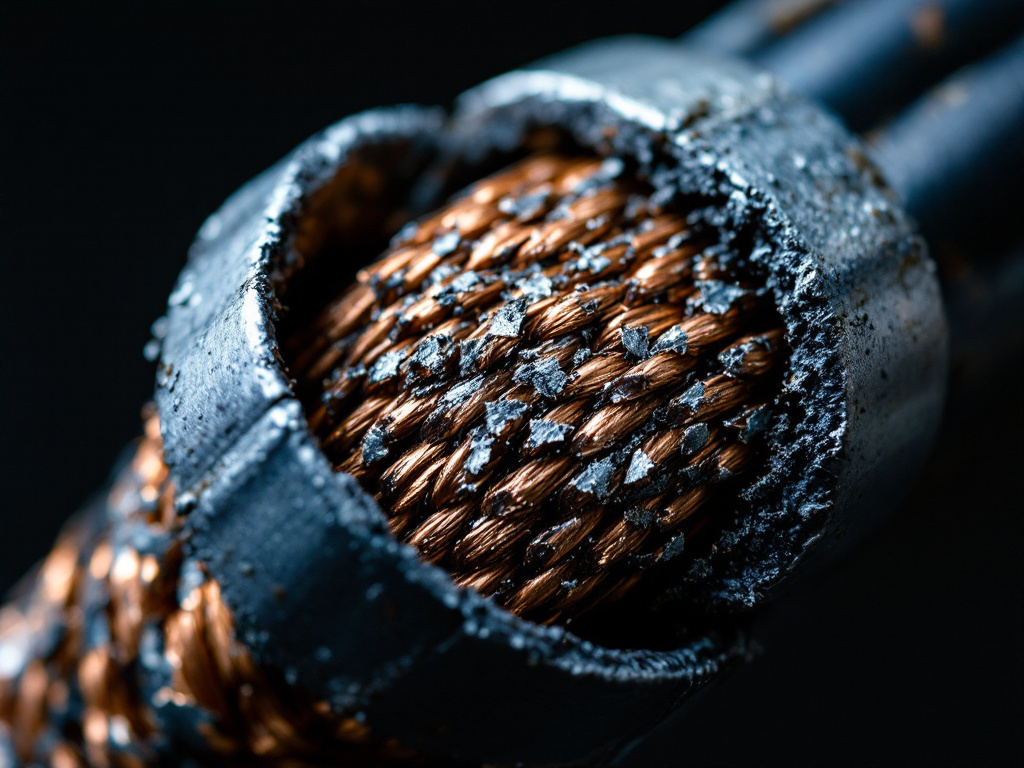
Yet, this ledger mechanism demands a physical reality that no longer exists. By standardizing copper at €5,000 per ton, the entity is hallucinating an economic environment insulated from absolute material scarcity. The CRU Group projects a global copper deficit of 1.5 million tons by 2027. While Nexans utilizes pass-through mechanisms in its contracts to mitigate raw material price volatility, a financial pass-through cannot resolve a physical shortage. Institutional capital cannot print physical metal out of thin air to fulfill high-voltage transformer orders.
When the demand signal for electrification outpaces the physical supply of conductive metals, the standardized baseline fails. The entity is locking in contracts for high-voltage cables based on a phantom price point, assuming that raw materials will materialize at a predictable rate. As the global copper deficit deepens, the raw material friction will dictate the pace of electrification, threatening to compress margins across Nexans’ entire PWR-Transmission segment.
Deciphering Organic Growth and Strategic Acquisitions
The tension between financial modeling and physical execution is further illuminated by the entity's aggressive mergers and acquisitions strategy. In corporate reporting, the phrase "organic growth" frequently serves as a linguistic shield, masking a reliance on strategic acquisitions to maintain upward momentum on top-line revenue charts. Nexans’ recent acquisition of Republic Wire—a United States platform generating approximately €520 million in annual sales—exemplifies this tactic.
Presented to institutional investors as a bold expansion into the North American grid transition, the acquisition of Republic Wire is fundamentally a defensive, capital-intensive maneuver. The United States grid requires a massive overhaul, but strict U.S. tariffs on imported aluminum and copper products have severely penalized foreign manufacturers. Nexans’ own "Other activities" segment recently reported a stark 24.1 percent organic decline, a direct casualty of these import frictions.
By deploying over half a billion euros to acquire Republic Wire, Nexans secures immediate, tangible access to domestic manufacturing capacity. It is a localized hedge designed to bypass the laws of state and localize the supply chain. However, this deployment of liquidity occurs precisely as European margins face compression from the impending copper deficit. The acquisition successfully papers over the structural decline in legacy segments, allowing the entity to report favorable growth metrics while avoiding the capital expenditure required to organically expand its own high-voltage manufacturing capacity.
The Battlefield of Apex Predators
The high-voltage transmission market is an unforgiving ecosystem, and Nexans does not operate in a vacuum. The entity is surrounded by apex predators actively eroding its market share and challenging its pure-player gospel. The competitive landscape in late 2026 is defined by aggressive technological deployments and predatory pricing strategies.
In September 2026, Prysmian Group launched a 525 kV HVDC (High Voltage Direct Current) cable system specifically engineered for offshore wind interconnectors. This deployment directly challenges Nexans’ dominance in the highly profitable offshore sector. Simultaneously, Southwire initiated an 8 percent price cut on medium-voltage distribution cables in October 2026, a move designed to undercut competitors and capture municipal grid upgrade contracts. Furthermore, LS Cable & System secured a $300 million United States grid modernization contract, proving that the North American market remains highly contested despite Nexans’ acquisition of Republic Wire.
Against this backdrop of fierce competition, Nexans’ narrative of "disciplined execution" faces internal contradictions. A critical component of the entity's offshore strategy relies on its cable-laying fleet. The third vessel in this fleet, the Nexans Electra, was slated to be operational by mid-2026. However, persistent industry reports confirm that the vessel's deployment has been delayed to the third quarter of 2026. In an environment where competitors are launching advanced HVDC systems and securing massive localized contracts, operational delays in critical deployment infrastructure represent a severe systemic vulnerability.
The Thermodynamic Bottleneck
Beyond the financial ledgers and the competitive battlefield, the ultimate governor of grid modernization is the law of physics. Nexans’ PWR-Transmission segment relies heavily on premium pricing for what it terms "high value-added solutions." Yet, these solutions are bound by the absolute conductivity limits of copper at high temperatures.
The architecture of the legacy grid was designed for heavy, predictable thermal baseloads—coal and nuclear power. The current mandate requires this same architecture to manage intermittent surges from offshore wind installations. Pushing volatile, intermittent power through legacy interconnectors generates immense thermal load. Upgrading this infrastructure requires not only high-voltage cabling but a massive deployment of new transformers.
According to Q3 2026 reports from the Transmission & Distribution (T&D) sector, transformer lead times have now extended to 18 to 24 months amid the ongoing copper shortage. This hardware deficit completely breaks the math of the forward-looking backlog. If the physical transformers required to step up and step down the electrical current cannot be sourced, the high-voltage cables cannot be installed. The €7.9 billion backlog ceases to be a metric of guaranteed future revenue; it becomes a concrete anchor of delayed projects, frozen capital, and unfulfilled municipal mandates.
The friction point is absolute. You cannot force an energy transition through a grid architecture that physically cannot carry the thermal load, and you cannot upgrade that architecture without the requisite copper.
The Concrete Anchor
The institutional capital forcing the market to upgrade its grids is operating on a timeline dictated by legislation, not material science. Nexans has successfully capitalized on this legislative urgency, building a pure-player narrative that satisfies the immediate demands of ESG-focused portfolios and government infrastructure mandates. The acquisition of Republic Wire and the reporting of a €7.9 billion backlog provide the necessary optical stability to keep analysts engaged.
Yet, as Bloomberg NEF noted in September 2026, copper scarcity will inevitably cap Nexans’ margin expansion, regardless of the size of its backlog. The demand signal for electrification is undeniable, but the physical supply chain required to execute it is deeply fractured. When a corporate strategy relies on standardized ledger mechanisms to mask physical scarcity, the resulting liability is simply deferred, not resolved.
Grid modernization is not merely a financial exercise in capital allocation; it is a heavy industrial undertaking bound by thermodynamics and raw material extraction. Until the physical deficit of copper and the 24-month lead times for vital hardware are reconciled, the multi-billion euro backlogs celebrated in corporate reporting will remain exactly what they are: a highly leveraged mirage.